
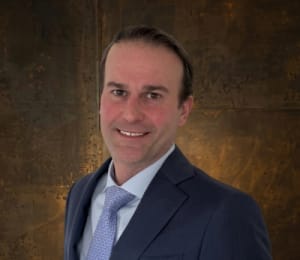
Justin Capetola
I didn't grow up dreaming of working in finance. I thought I'd be playing college sports — football, basketball, baseball, every season. Sports gave me structure and focus.
Then junior year, a knee injury pulled me off the field, and the future I'd been aiming for disappeared. Looking back, that was my first lesson in pivoting with purpose. When the plan changes, you adapt, get clear on what matters, and build a new path forward.
I was raised in a family of high performers — doctors, scientists, PhDs. I'm the only one who went into finance, but being surrounded by people who asked big questions and pushed for clarity shaped how I think. Good financial advice isn't just math — it's helping people see clearly when things feel overwhelming.
Running became my new outlet. I picked up running in my late 20s, training myself at first — checking in on my breathing, my mindset, whether I was pushing too hard. I hit a plateau eventually, and did something most high-achievers struggle with: I asked for help. Hiring a coach made me faster, smarter, and more consistent — and it mirrored a lot of what I now talk through with clients.
I'm a husband, dad to three kids, and coach for my son's sports teams. Life is full and moving fast — I'm in the thick of it, just like the families I work with. That gives me a front-row seat to what matters most: time, clarity, and confidence.
Your finances aren't a DIY project. Sure, you can do it yourself — but at some point the strategies that got you here stop working. Big income, stock options, 401(k)s, estate plans, kids, aging parents, limited time. This is where I come in — not with a cookie-cutter plan, but a calm, experienced, long-view approach rooted in real life.
I've been a financial advisor for 20 years. I don't lead with spreadsheets or fear tactics. I lead with curiosity, strategy, and respect for the trust my clients place in me.
If you've ever thought "we're doing okay, but I don't know what I'm missing", you're in the right place. Book a 20-minute free consultation call with me.
______________________________________________________________________________
5 FAQs
1 How much money do I need to have to work with an advisor?
A: We don't have strict minimums, but $250,000 in investable assets (excluding your 401(k)) is generally a good starting point for our services. If you're close to that threshold or have a complex financial situation, we can help you determine if we're a good fit. You can schedule a time to talk below.
2 How do you get paid? Are there any fees?
We charge an assets under management (AUM) fee, which for most clients comes out to around 1% of the assets we directly manage.
What's included in that fee:
• Financial planning and retirement planning
• 401(k) optimization and guidance
• Social Security planning
• Tax planning strategies
• Ongoing support and reviews
You're not charged extra for calls, emails, or questions. Our fee covers the full relationship.
3 How does the relationship work? What does ongoing communication look like?
Think of us as your financial partner, not just an advisor you meet with once a year.
Here's how it works:
• You'll have direct access to me: my cell phone, email, all of it
• If anything comes up (a question, a life change, a decision you're working through), reach out anytime.
• We typically respond within 24 hours
• You're never charged per conversation, our relationship is ongoing.
• We'll also schedule regular reviews to make sure your plan is on track and adapts as your life changes.
4 How are you different from other financial advisors?
Most advisors focus on managing your portfolio. We focus on helping you make better decisions.
Here's what that means:
• We tie your finances to your real life: your family, your goals, your values
• We act as your coach, not just your money manager
• We care about you and your family, and we take the time to understand what really matters to you
If you want a partner who sees the full picture and helps you navigate life's biggest financial decisions with confidence, that's what we do.
5 How do I know if I'm ready to work with a financial advisor?
You might be ready if any of these sound familiar:
• You and your spouse are having conversations about money but not making progress
• You're thinking, "I can't do this on my own anymore"
• Your financial life is getting complex: multiple accounts, aging parents, business income
• You're going through a big life change: kids going to college, death of a parent, having your first child, changing jobs
• You're approaching 40 (or beyond) and realizing you need a real plan, not just good intentions
Justin Capetola Insights

Software Stocks Are Getting Hit Hard. Here's Why We Don't Try to Ride It Unhedged.
Blue Bell Private Wealth Management Welcomes Sean Miller as Investment Advisor Representative
Merck Offers Both a Pension and a 401(k). Are You Maximizing Both?
Structured Products Explained
Case Study: How a Merck Director in Upper Gwynedd Reduced Her Tax Bill by $28,000 — While Eliminating a Major Concentration Risk
Stock Options, Kids, Retirement: How High-Earning Couples Can Finally Get Financially Organized
